Research library

Evidence for better operating questions.

Review source-led briefs and proposed protocols for examining receivables workflows, evidence quality, handoffs, and role boundaries.

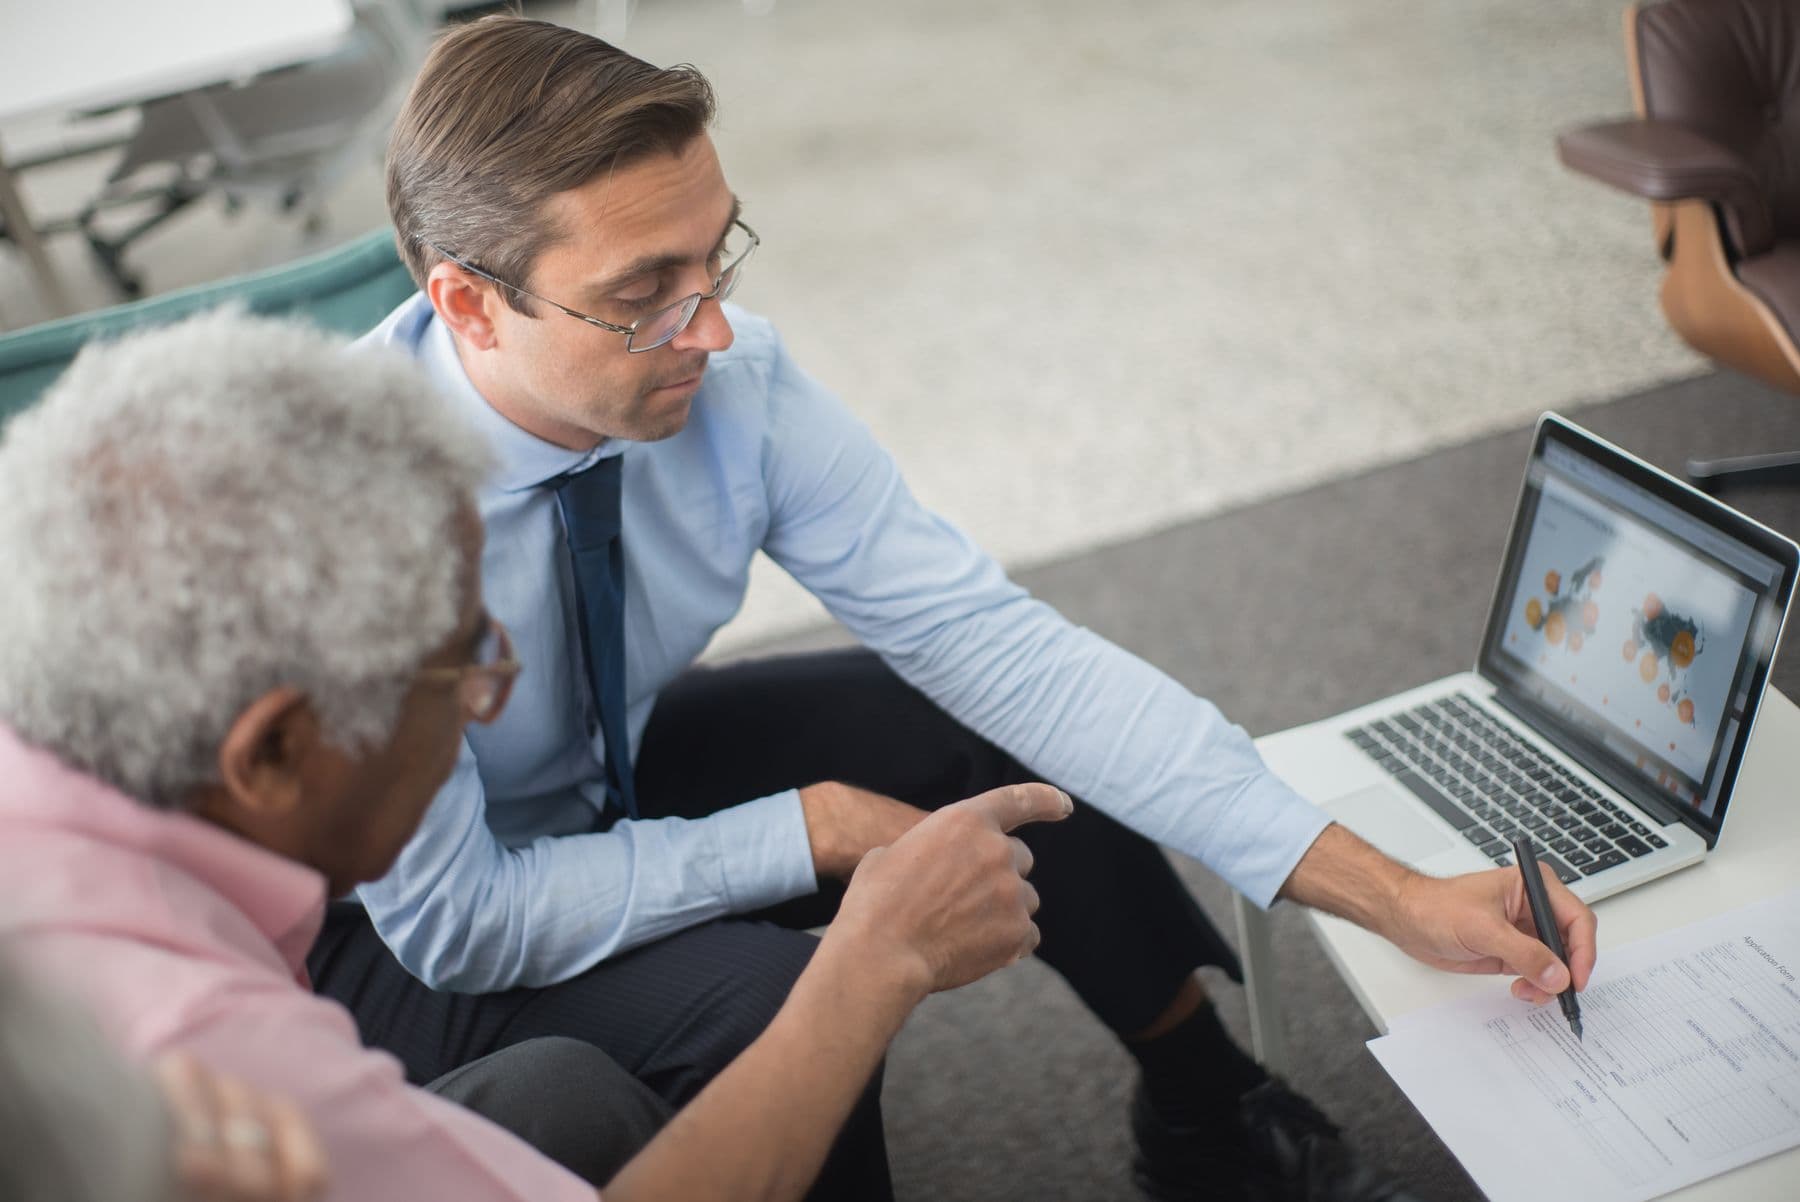
Finance professionals reviewing a receivables source document beside a laptop
QuestionDefine the queue and observationEvidenceName sources and limitationsReviewKeep operating judgment with the owner

Reading the library

Separate study design, observation, and operating judgment.

Use the topic and status shown on each brief to choose a relevant question. Proposed protocols explain how a study could be run and do not claim completed results. Review source links and limitations before applying any interpretation.

Research ledger

Browse every brief

Each brief identifies its topic and protocol status before you open the full methods, limitations, sources, and related workflow path.

Cash application research · Proposed protocol

Partial Payment Allocation Decision Repeatability

A reproducible protocol to measure whether independent reviewers classify the same partial-payment allocation evidence consistently, with evidence lineage, reviewer checks, privacy safeguards, and transparent limits.

8 min read
Review the brief
Cash application research · Proposed protocol

Lockbox Import Reconciliation Completeness

A reproducible protocol to measure whether lockbox imports retain complete file, control-total, reject, duplicate, variance, and approval evidence, with evidence lineage, reviewer checks, privacy safeguards, and transparent limits.

8 min read
Review the brief
Cash application research · Proposed protocol

Reviewer Agreement in Cash Application Proposals

A reproducible protocol to test whether independent reviewers reach the same evidence classification for proposed cash applications, with evidence lineage, reviewer checks, privacy controls, and explicit limits.

8 min read
Review the brief

From question to workflow

Place evidence inside clear decision boundaries.

Use a brief to identify what should be measured, who should review it, and which decisions remain with your accountable finance team.

Discuss your workflow